
Enjoy a brief glossary to enhance appraisal expertise, diving into personal and real property, personalty, valuation vs. evaluation, and more.
One hundred and forty-eight years ago, a patent introduced an asbestos cigarette. Yes, paper was eliminated and replaced with an asbestos tube because, as the patent stated, "The object of the invention is to devise means for doing away with the rolling up of the tobacco in paper wrappers, and to obviate the injurious effects produced by the burning of said wrappers on the health of the smoker."1 Are you gasping at the lack of scientific know-how? Cigarette paper is practically benign in comparison to as bestos and tobacco! Appraising, too, is often lacking in some basic skills. Let's start with a real and personal property glossary to enhance our expertise.
Your Move
What is real and personal property? It is a matter of mobility. Real property is immovable, and personal property is movable.2 Real property usually is land, buildings on the land, and personal property attached to the land or building on the land: "Real property: Relating to land, as distinguished from personal property. This term is applied to lands, tenements, and hereditaments."3 Basically, a ceiling fan would be personal property until it is attached to a ceiling, then it becomes real property. Appraisers unanimously agree that a house is real property. But is it?
An interesting precedent-setting court case involved a house that was detached from the ground and placed on a moving truck to be hauled to a different lot. While on the truck, the house caught fire and burned. The court reclassified the house from real property to personal property since it was no longer attached to the ground. Thus, the owner only received the building's reasonable cash value instead of the insurance policy's face value.4
Personal property can be defined as such: "Every kind of property that is not real is personal."5 Is that all?
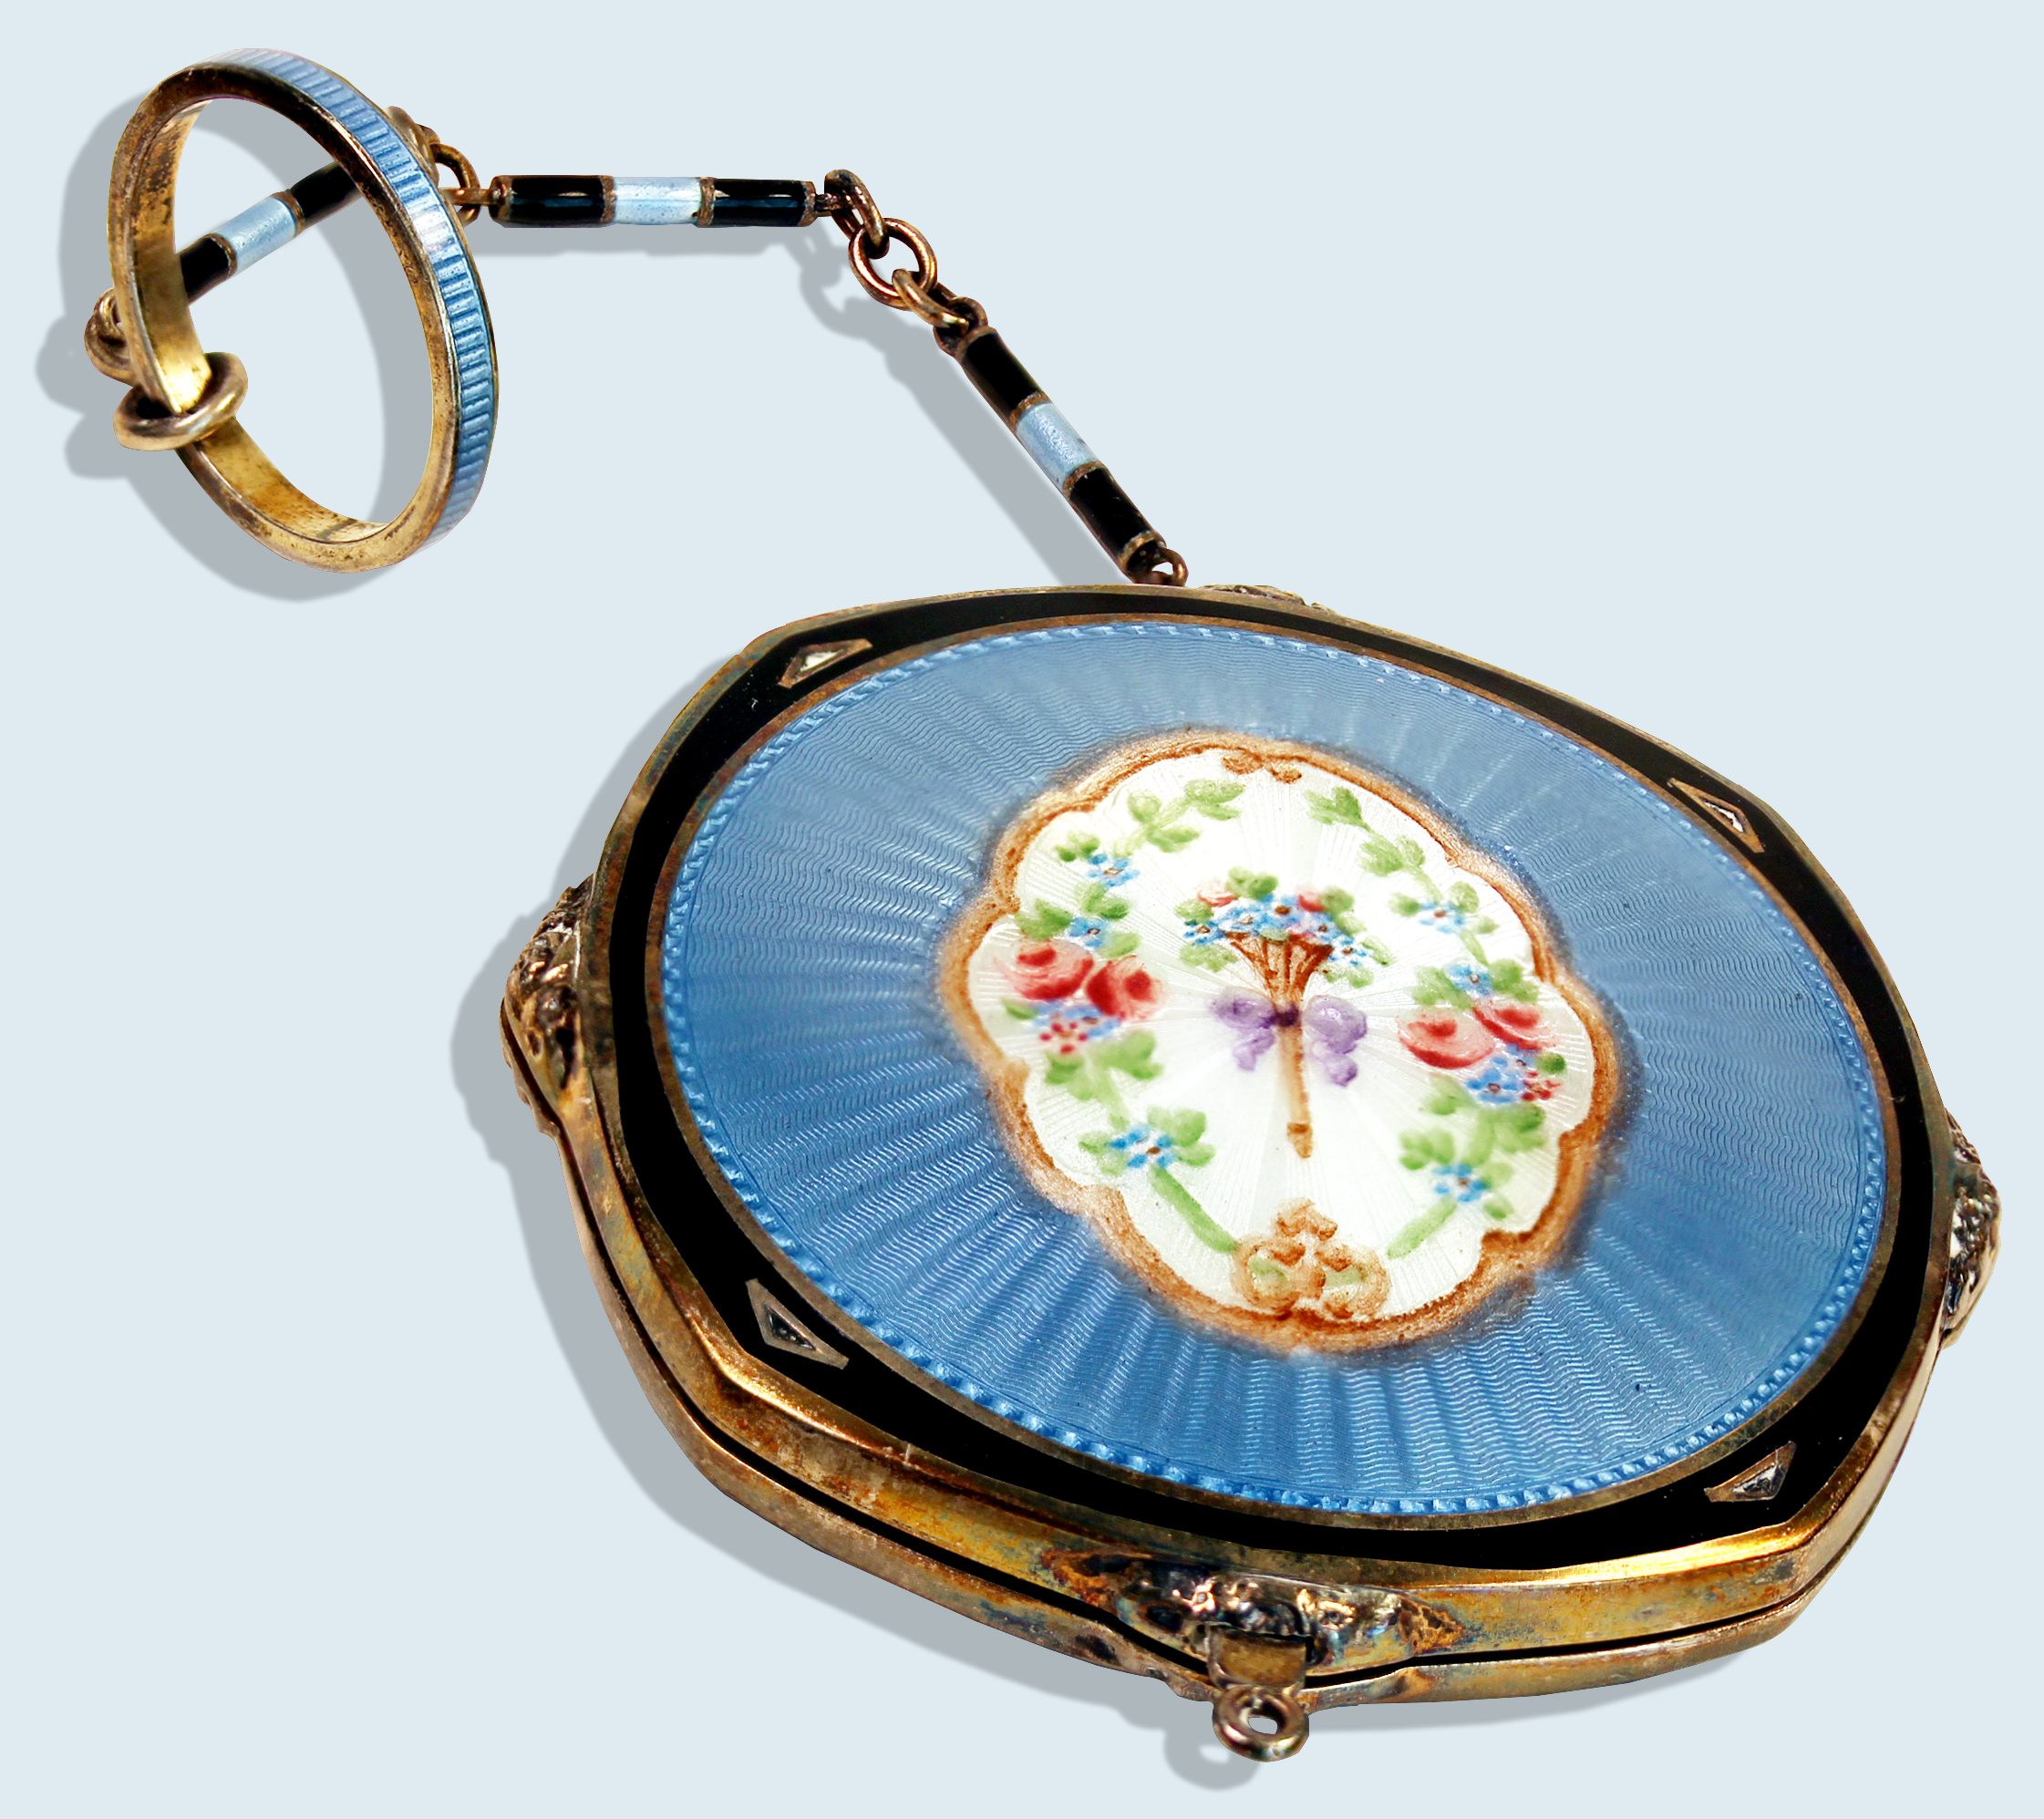
Enameled Silver Flapper Compact Case, circa 1920s, owned by author.
Chattel Tales
There are other terms used for personal and real property. There are personal chattels and real chattels. "Personal chattel: Movable things. Personal property, which has no connection with real estate. Real chattels: Such as concern real property . . . "6 A New York, Feb. 15, 1855, appraisal stated, "A true and perfect inventory of all goods, chattels, and credits of [name redacted] late of the town of Germantown in the county of Columbia, deceased, made by [name redacted]."
And, if that's not enough, there is personalty. No, it is not a misspelling. "Personalty: Personal property; movable property; chattels."7 There is tangible and intangible personal property. Intangible personal property involves legal rights. For example, if you have a stock certificate, it represents a type of ownership, and thus it is an intangible personal property. But, if the stock certificate does not represent ownership as a shareholder, and it is a collector's item, then it is tangible personal property.
Jewelry is personal property, personal chattel, and personalty.
Get a Grip
Tangible personal property can be either appreciable or depreciable. These personal property types are based upon value. Is the property increasing in value? Then it is appreciating. Is it decreasing in value? Then the property is depreciating. Some appraisers will add an inflation factor to their value conclusion. The idea is to get proper insurance coverage in a rising market. Often, the appraiser is also the vendor, and the appraisal is a "feel good" aspect of the sale. Do not do this. Instead, merely state the value determined as of the effective date (date of value).
Switching Gears
An easy pair of terms to define are the insured and the insurer. "The person who undertakes to indemnify another by insurance is the insurer, and the person indemnified is the insured."8 Notice the word indemnify in the definition. This is the backbone of insurance and the goal of appraisers to report as value in an appraisal intended to be used to obtain insurance as well as some other insurance-related valuation assignments. The insurer is the insurance company, whereas the insured is the person or entity the insurance company is insuring. To further emphasize indemnity, let's define insurance. It is: "A contract whereby one undertakes to indemnify another against loss, damage, or liability arising from an unknown or contingent event and is applicable only to some contingency or act to occur in future."9 Again, insurance is a contract of indemnity.
What is the difference between valuation and evaluation? "There are two basic appraisal steps: (1) evaluation and (2) valuation. A simple definition of valuation is a process of determining an item's worth . . . A simple definition of evaluation is a process of determining an item's quantitative and qualitative elements."10 In other words, evaluation is what you do when you identify gemstones, grade them, ascertain the metal, providence, etc. an item of jewelry.
A Matter of Policy
The two types of insurance policies that are most likely to be encountered by appraisers are agreed value policies and actual cash value policies. An agreed value policy is also called a valued policy and a cash policy. "A valued policy is one which expresses on its face value an agreement that the thing insured shall be valued at a specific sum."11 In other words, the value agreed to when obtaining insurance is what will be paid in the event of a casualty loss.
The conventional definition for an actual cash value is taught as "replacement cost minus depreciation and obsolescence." But wait, that definition only applies in certain jurisdictions. A short history lesson will serve to clear this up. If a contract of indemnity does not exist, damages are determined by establishing the values before and after a loss has occurred. If the item no longer exists, then the value is zero for the after calculation. This difference in value is called compensatory damages.
Of course, insurance is different because the damages are determined by contract. If there is no definite value definition within the insurance policy, then the legal arena has one to use. Actual cash value has two ancestral options. Each state has what are called statutory forms for Homeowners' Policies use within that state as of the 1940s. A Homeowners' Policy is also called a Fire Insurance Policy. Thus, states are either a pendant state of the Massachusetts Standard Policy or the New York Standard Fire Policy.12
The Massachusetts Standard Policy came to be in 1882: " . . . does insure . . . and legal representatives, to the extent of the actual cash value of the property at the time of loss . . . "13 Two pendant states that follow the Massachusetts Standard Policy are Minnesota and New Hampshire.14
The New York Standard Policy came to be in 1886. "In consideration of the provisions and stipulations herein or added hereto and of . . . dollars premium this company . . . to an amount not exceeding . . . . dollars, does insure . . . and legal representatives, to the extent of the actual cash value of the property at the time of loss, but not exceeding the amount which it would cost to repair or replace the property with material of like kind and quality within a reasonable time after such loss . . . "15 The amount paid would be the lesser of two options, actual cash value or replacement value.
Regardless of what type of policy will be used, an appraiser should render the valuation report with a defendable value that would achieve indemnity in the event of a loss as of the effective date.
Written by Bill Hoefer
|
|
|
|
|
|
1. Asbestos Cigarette, invented by William Brisbane, No. 198,075, patented Dec. 11, 1877. Back to Text ↑ ↑ ↑
2. California Civil Code § 657. Back to Text ↑ ↑ ↑
3. Black's Law Dictionary, Fifth Edition, page 1137. Back to Text ↑ ↑ ↑
4. 364 S.W.2d 771. Back to Text ↑ ↑ ↑
5. California Civil Code § 663. Back to Text ↑ ↑ ↑
6. Black's Law Dictionary, Fifth Edition, page 215. Back to Text ↑ ↑ ↑
7. Ibid. Back to Text ↑ ↑ ↑
8. California Insurance Code § 23. Back to Text ↑ ↑ ↑
9. Black's Law Dictionary, Fifth Edition, page 721. Back to Text ↑ ↑ ↑
10. Advanced Personal Property Appraisal (APPA) course, by William D. Hoefer, Jr., page 59. Back to Text ↑ ↑ ↑
11. 2013 North Dakota Century Code, Title 26.1 Insurance, Chapter 26.1-30-03(3). Back to Text ↑ ↑ ↑
12. American Bar Association, Property Insurance Annotations Fire & Extended Coverage 3-5 (1997). Back to Text ↑ ↑ ↑
13. Massachusetts General Laws Annotated, Chapter 175, § 99. Back to Text ↑ ↑ ↑
14. Minnesota Statutes Annotated, 7, §65A.01 and New Hampshire Revised Statutes Annotated, Chapter 407.22. Back to Text ↑ ↑ ↑
15. McKinney's Consolidated Laws of New York, annotated, Book 27, § 3404. Back to Text ↑ ↑ ↑
16. Published in Gem Guide, May-June 2025, Volume 44, Issue 3, pages 29-30.
17. Article illustrations by Bill Hoefer.
18. Other illustrations - IStock.com.