
Appraisers may rely on auction results to determine fair market value for estate tax purposes, but is that enough?
Imagine bidding at an auction for the Roman Empire! The Praetorian Guard, the empire's secret police, had slain Emperor Pertinax. Sulpicianus, the emperor's father-in-law, offered the guard 5,000 drachmas per soldier to make him emperor. So much for family loyalty. Instead, the guard chose to auction the Roman Empire in a public auction. On March 28, 193 A.D., rich senator Didius Julianus won the empire with a bid of 6,250 drachmas per soldier and was declared emperor. However, that initiated a civil war involving the armies of Britain, Syria, and Pannonia. The Praetorian Guard eventually deserted the highest bidder and emperor, and he was both convicted and beheaded by the Roman Senate!1
Most appraisers rely on auction results for determining fair market value for estate tax purposes. But does reliance on auction results avoid being beheaded by Internal Revenue Service (IRS) auditors?
We Assume No Liability
Auctions usually rely on all-encompassing disclaimers such as, "No warranty, whether expressed or implied, is made with respect to any description contained in this auction, or any second opine. Any description of merchandise or second opine contained in this auction is for the sole purpose of identifying merchandise for those bidders who do not have the opportunity to view merchandise prior to bidding, and no description of merchandise has been made part of the basis of the bargain or has created any express warranty that merchandise would conform to any description made by auctioneer."
Thus, are the descriptions in an auction catalog trustworthy?
The IRS requires fair market value for determining estate tax. There is a definitive fair market value definition provided in the federal regulations. It declares, "The fair market value is the price at which the property would change hands between a willing buyer and willing seller, neither being under any compulsion to buy or sell and both having reasonable knowledge of relevant facts. The fair market value of a particular item of property includable in the decedent's gross estate is not to be determined by a forced sale price. Nor is the fair market value of an item of property to be determined by the sale price of the item in a market other than that in which such an item is most commonly sold to the public, taking into account location of the item wherever appropriate. Thus, in the case of an item of property includable in the decedent's gross estate, which is generally obtained by the public in the retail market, the fair market value of such an item of property is the price at which the item or a comparable item would be sold at retail."2
Whew! The portion to pay close attention to is when it mentions sales to the public and the sale is retail.
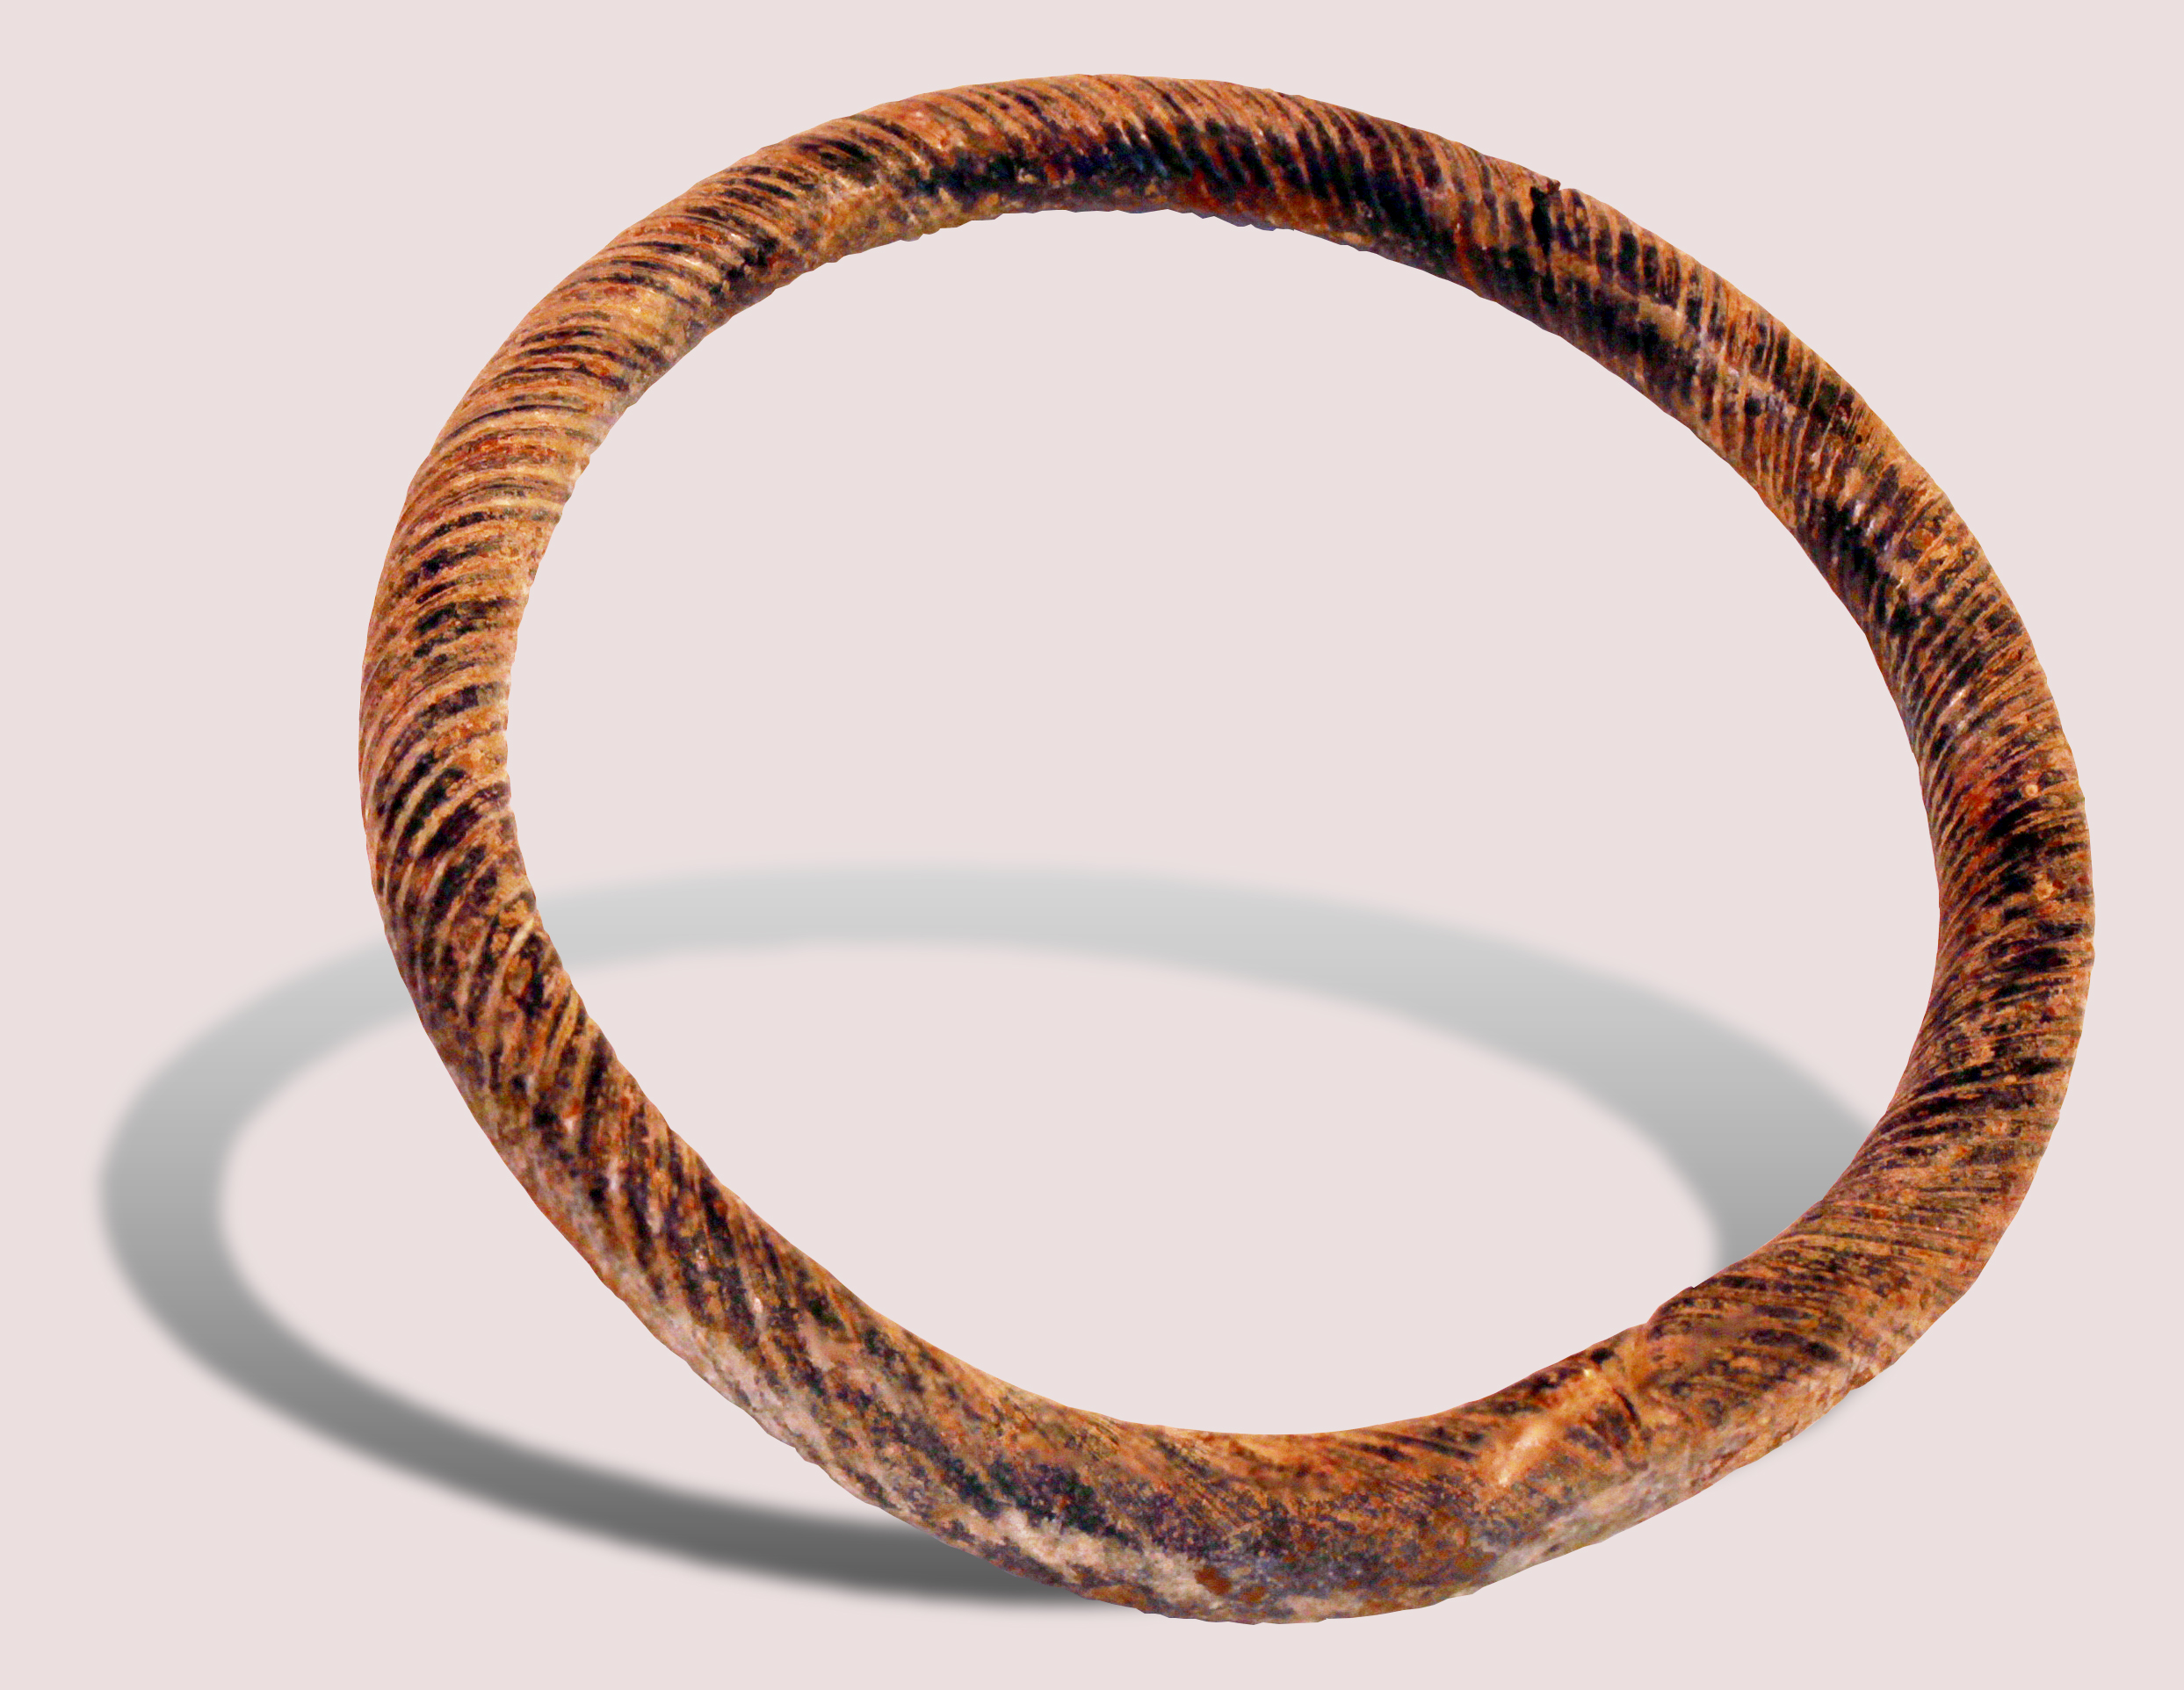
Roman glass bangle from 100 to 300 A.D., owned by author.
Precedent-setting tax court cases have published and finetuned the IRS' fair market value definition. One such court stated, " . . . opined that the public usually buys jewelry at retail from jewelry stores that sell estate jewelry, that the majority of buyers at public auctions are dealers, that the lowest level of sales prices for jewelry is found at auction, and that jewelry usually passes from the dealer to the public through retail jewelers with a dealer-to-retail jeweler markup . . . ." 3 In other words, unless one is certain the auction's sales were to the public and not to dealers, such sales may not be to the "ultimate consumer."
Of course, if the items sold at an auction are to the ultimate consumer, then they do fit the IRS' definition. One tax court concluded that, "Petitioners assert that prices obtained at public auction sales should be disregarded as they represent a 'disorderly market,' do not reflect real value, and are wholesale prices, i.e., many purchases at such sales are by art dealers for resale. We are not persuaded by petitioners' arguments and agree with respondent that auction sale prices are relevant to the determination of fair market value in this case. The controlling question is whether art auction sales represent sales to the ultimate consumer, not whether identical 'consumer' prices are also available to dealers. It is clear that a significant number of auction sales are to consumers, and this court has previously recognized the significance of such sales in determining the fair market value of art."4
Musical Markets
Rather than play musical markets, not knowing if you can make it to a chair quick enough to not be eliminated from the game when the music stops, render an appraisal that reports all possible market results. This is called the broad evidence rule. Broad evidence came to be for reporting more than one market for insurance casualty loss valuation scenarios. Thus, if a casualty loss occurs and a court or appraisal dispute panel is to establish actual cash value, in some states, any evidence that would determine a value can be shown - the allowance of all value research to prove the value of an item. Or as a court defined it, " . . . The broad evidence rule permits the consideration of all evidence logically related to the formation of an accurate estimate of the value of the destroyed or damaged property, for the purpose of ascertaining the 'actual cash value' at the time of the loss. In applying this rule, it is not necessary to abandon considera tion of either market or reproduction values, but they must be viewed merely as guides and not the sole determinative in arriving at 'actual cash value.'"5
How does this work in practice? If you are valuing a retro era wedding ring, is the most appropriate market selection an estate jewelry store or an auction? Applying broad evidence methodology solves the predicament. Report values from each market. Remember that the basic premise of an appraisal is to convey information, therefore the broad evidence rule fits that objective.
Even if your values do not achieve the minimum for the federal tax to apply, it is the entire estate's value that determines if the tax applies. Thus, even with low value totals in an estate appraisal, always render it in compliance with the federal and the state of jurisdiction's rules. If the value definitions are different and that makes a difference in the values determined, then render a broad evidence-based report.
Written by Bill Hoefer
|
|
|
|
|
|
1. Gibbon, E. (1776). The History of the Decline and Fall of the Roman Empire, Chapter V, Volume I. Back to Text ↑ ↑ ↑
2. 26 Code of Federal Regulations § 20.2031-1(b). Back to Text ↑ ↑ ↑
3. T.C. Memo. 2004-27, 2004 WL 205824, 87 T.C.M. (CCH) 851, T.C.M. (RIA) 2004-027, 2004 RIA TC Memo 2004-027. Back to Text ↑ ↑ ↑
4. T.C. Memo. 1985-315, 1985 WL 14942, 50 T.C.M. (CCH) 266, T.C.M. (P-H) P 85,315, 1985 PH TC Memo 85,315. Back to Text ↑ ↑ ↑
5. 77 N.J.Super. 531, 187 A.2d 49." Back to Text ↑ ↑ ↑
6. Published in Gem Guide, July-August 2026, Volume 44, Issue 4, pages 21-22.
7. Article illustrations by Bill Hoefer.
8. Other illustrations - IStock.com.